When Salary Becomes a Debt Collection Tool.
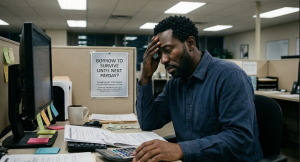
Sometimes, the biggest financial problem an employee faces is not how much they earn, but how often they have to borrow to get through the month.
It often starts with something small. An employee receives their salary, pays the usual bills and sets aside money for household expenses. Everything appears manageable until an unexpected expense comes along.
Perhaps school fees increase. The landlord gives notice of a rent adjustment. A family member needs financial assistance. An emergency comes up, or an existing loan repayment leaves less money than expected.
The employee needs money, and borrowing seems like the easiest solution.
A mobile loan is taken. A salary advance is requested. A colleague offers a short-term loan. The immediate problem is solved, and life continues.
But then payday arrives.
Before the employee can address the next month’s expenses, the loan repayment is due. Another deduction comes in. The employee is left with less disposable income than before, and the same financial pressures are still waiting.
So they borrow again.
Over time, what started as occasional borrowing can become a routine way of managing everyday expenses.
This is one of the financial realities that employers may not always see. An employee can have a permanent job, receive a regular salary and still depend on short-term borrowing to maintain their household.
The challenge is that borrowing can gradually become part of an employee’s monthly financial structure. Instead of using credit to finance a planned investment or manage a temporary emergency, they begin using it to fill recurring gaps in their income.
And when borrowing becomes repetitive, the cost is not always limited to interest and repayment charges. It can also reduce financial flexibility, limit the ability to save and make even minor emergencies difficult to manage.
For the employee, this can create a cycle that is difficult to break. They may want to save but have no money left after deductions. They may want to clear existing loans but keep taking new ones. They may understand that borrowing is becoming expensive but struggle to identify another way of meeting their obligations.
This is why financial literacy in the workplace should not be reduced to encouraging employees to avoid loans.
Employees need to understand when borrowing is appropriate, how to assess affordability, how multiple credit facilities affect their disposable income and how to develop a realistic debt repayment strategy.
They also need practical guidance on building emergency reserves, prioritising financial commitments and recognising the warning signs of unsustainable borrowing.
For HR and People & Culture teams, this presents an important consideration:
Are employees being equipped with the financial knowledge to make informed borrowing decisions, or are we only discovering their financial difficulties when they begin affecting the workplace?
Financial wellness does not mean employers should take responsibility for employees’ personal finances. Neither does it mean monitoring who borrows or how much they owe.
It means recognising that financial capability is an important part of employee well-being and creating opportunities for employees to access practical, confidential and non-judgmental financial guidance.
Sometimes, an employee does not need another salary advance. They need help understanding why their salary is consistently running out, how their debts are affecting their finances and what practical steps can help them regain control.
If your organisation is investing in employee well-being, financial literacy and responsible borrowing deserve a place at the table.
Because helping employees earn an income is important. Helping them understand, manage and protect that income is equally important.
A financially informed employee is better positioned to make decisions today without compromising their financial stability tomorrow.
#HRKenya #KenyanEmployers #COTUKenya #FKEKenya #KEPSA #KNCCI #TradeUnionsKenya #LabourRelations #EmployeeWellbeing #EmployeeFinancialWellness #FinancialLiteracyKenya #WorkplaceWellness #ResponsibleBorrowing #DebtManagement #FinancialInclusion